Please note: the position on Labuan business activities that are not listed in the Regulations is not yet settled in practice, despite the judicial review decisions described below. Please speak to us before relying on this article for your own entity.
Updated: Mar 7, 2025
AN UPDATE arising from the successful resolution of Judicial Review applications
Labuan companies carrying on business activities, whether licensed or non-licensed, are regulated under the Labuan Companies Act 1990 and the Labuan Financial Services and Securities Act 2010 where applicable. Whereas the tax and the economic substance requirements for each type of Labuan business activity are covered under the Labuan Business Activity Tax Act 1990 (“LBATA”).
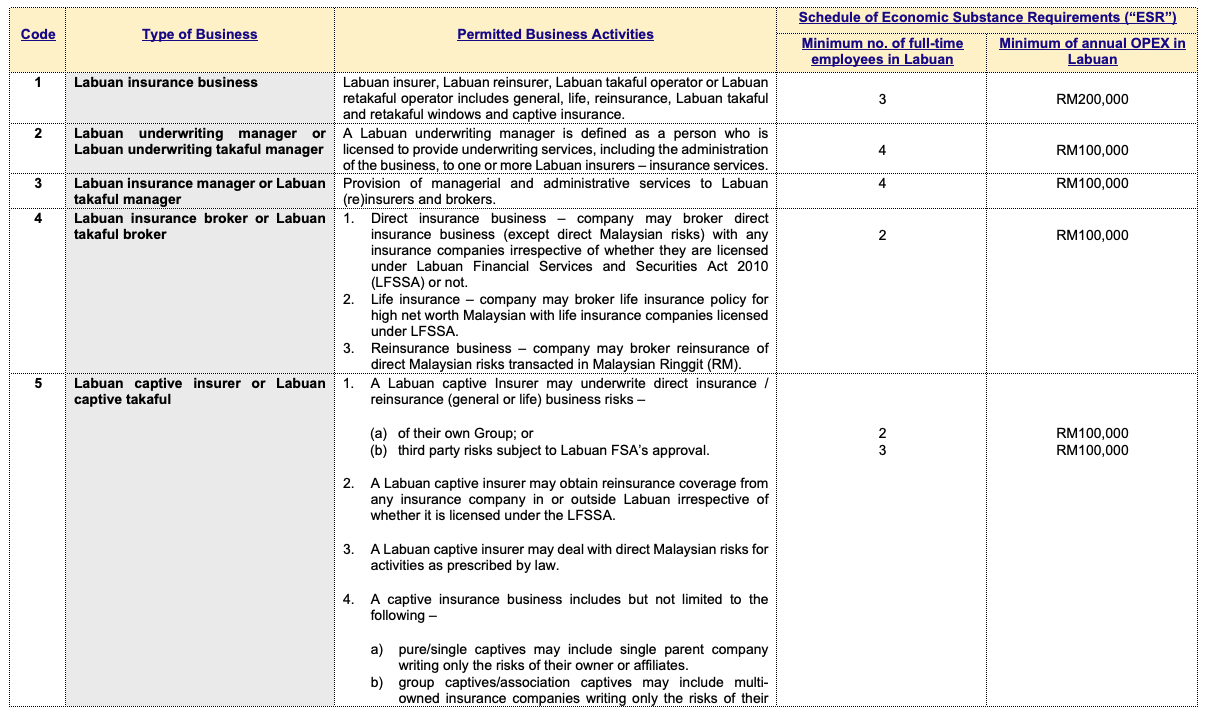
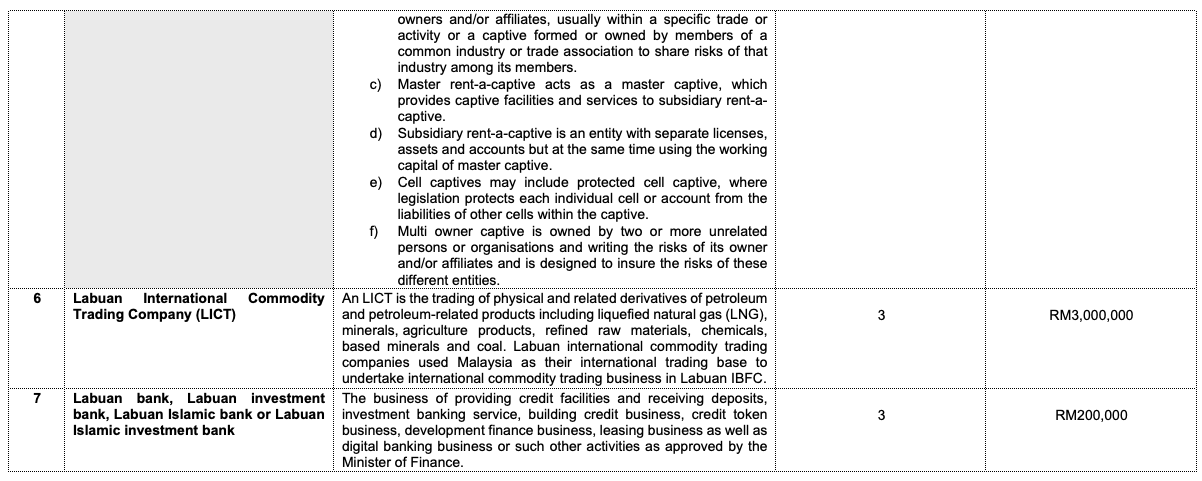
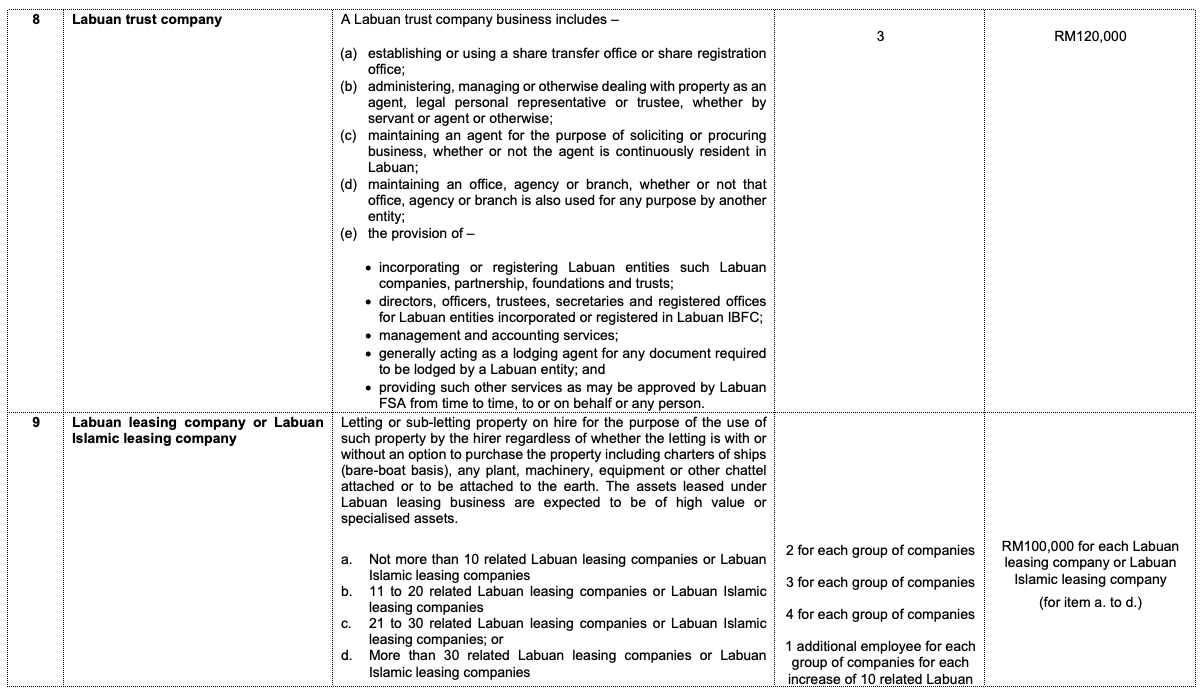
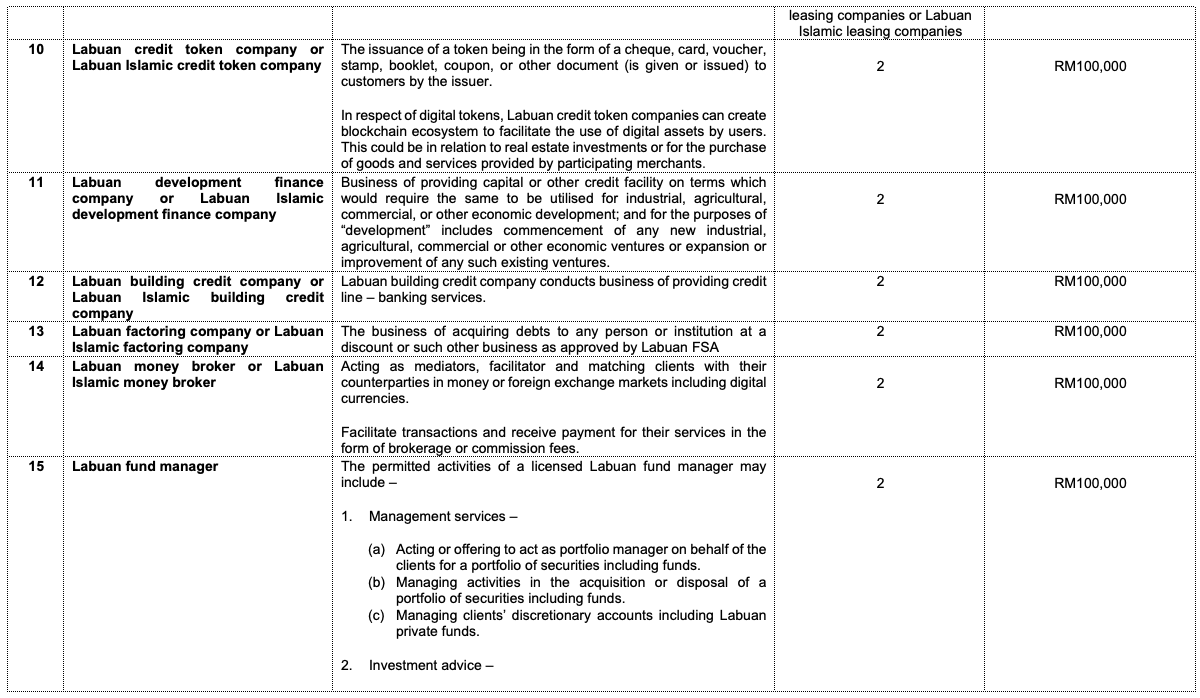
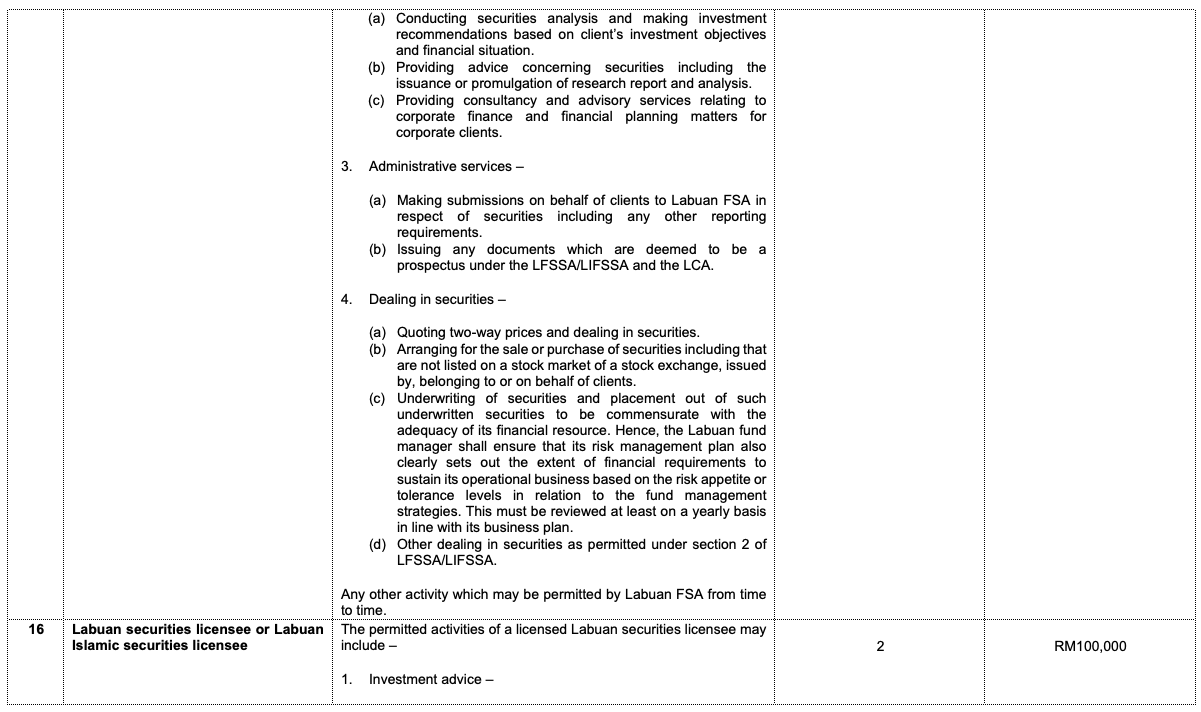
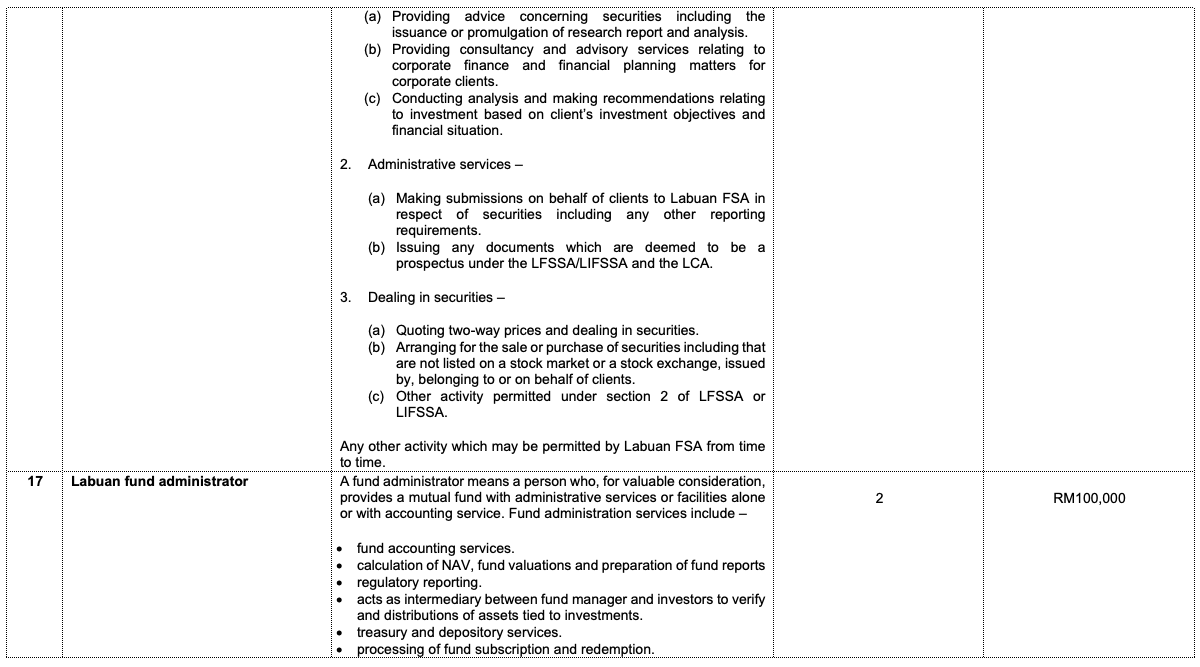
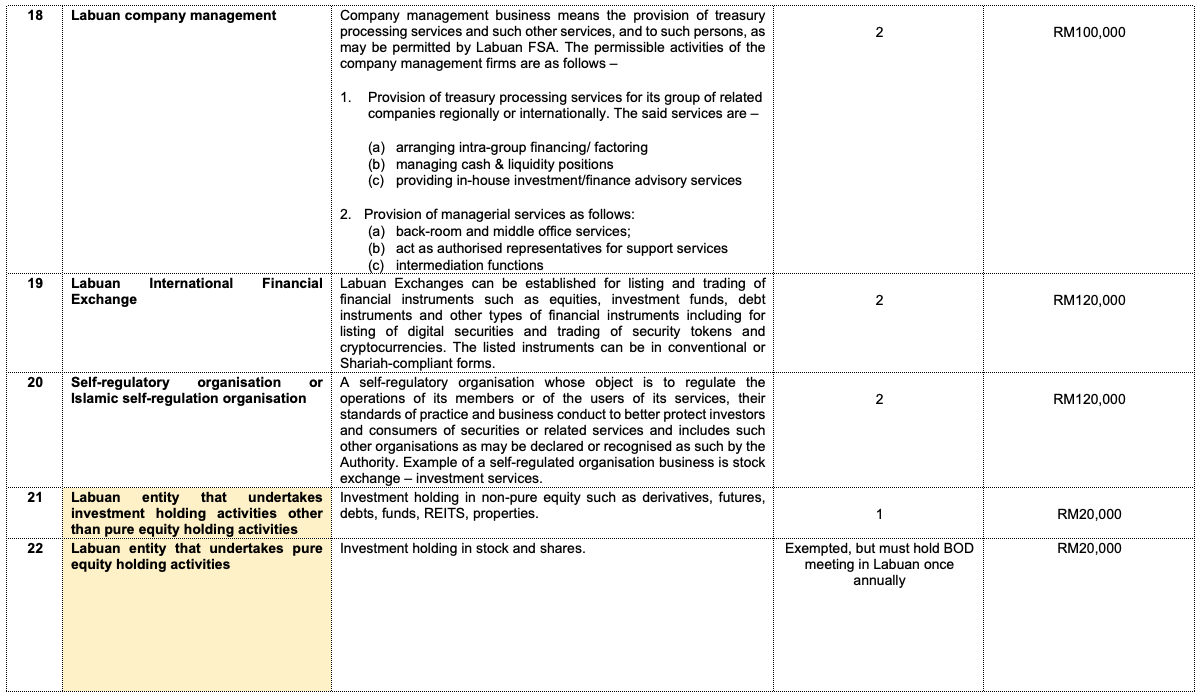
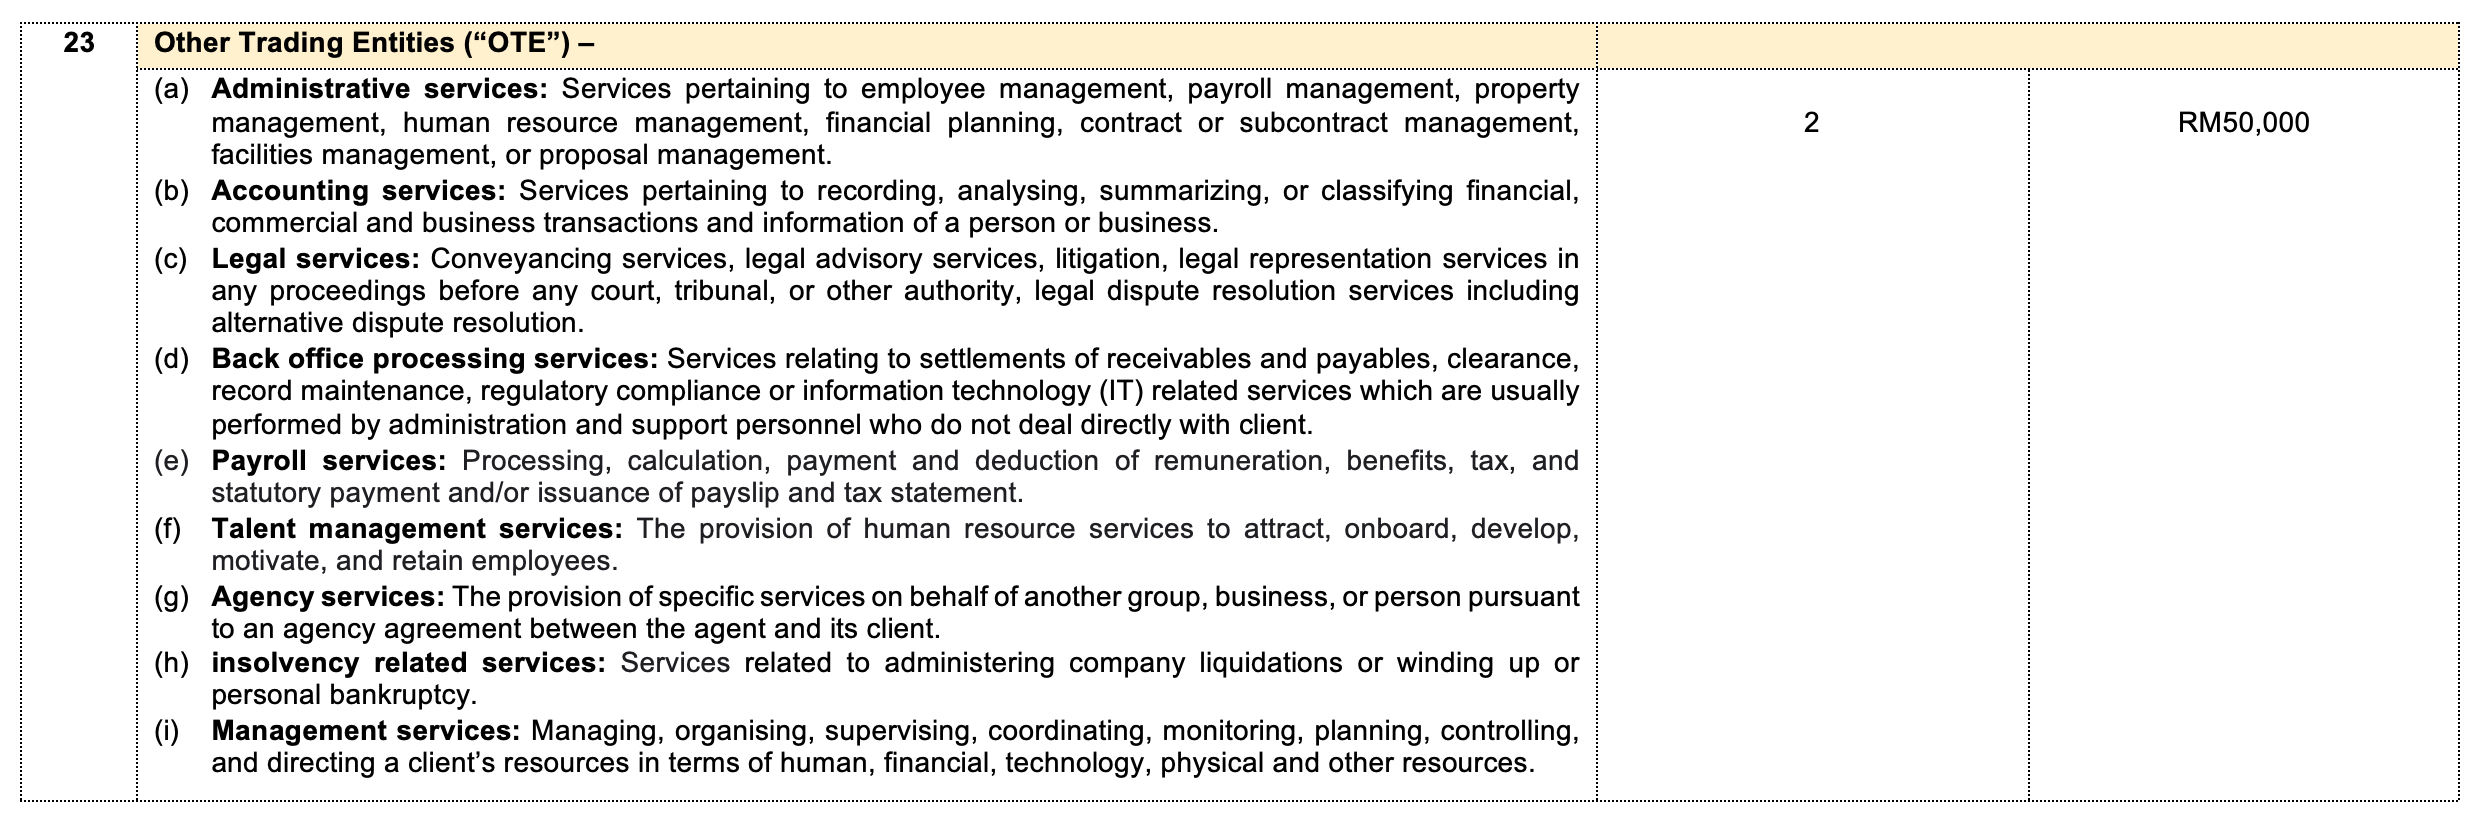
Permitted Labuan business activities are categorised and defined in the table provided below showing the minimum economic substance requirements (“ESR”) to comply under the LBATA in order to benefit from the preferential tax rates of 0%-3%.
"Labuan business activity' is defined as a Labuan trading or a Labuan non-trading activity carried on in, from or through Labuan .
Labuan entity that undertakes 'Labuan business activity' other than Labuan business activities specified under the codes below DOES NOT REQUIRE TO COMPLY WITH ESR.
Please note that a business activity that earns royalty and other income derived from intellectual property rights (IP rights) will be assessed and taxed under the domestic Income Tax Act 1967.
Note: Business activities under codes 1 to 20 require licensing from Labuan FSA .
What follows is the Schedule itself, reproduced as published. Each row gives an activity code, what that business is permitted to do, and the two numbers that decide your tax position — the minimum fit and proper full-time employees you must have in Labuan and the minimum you must spend there each year.
It runs to eight pages. If you only need your own two numbers, the searchable table above gives them without the statutory wording; these pages are here so you can read the full definition of your activity, which is what an assessment will actually turn on.