This summary of information is prepared based on the prevailing laws, guidelines issued by Labuan FSA, and our current fee schedule. All information is accurate at the time of publication. For further assistance, please contact our Konsultan .
Key Criteria for Labuan Private Funds
Investor Limits and Minimum Investment:
Up to 50 investors, each with a minimum initial investment of RM250,000 (or equivalent in foreign currency); or
Unlimited investors, each with a minimum initial investment of RM500,000 (or equivalent in foreign currency).
Eligible Labuan Entities
· Labuan Company
· Labuan Protected Cell Company (PCC)
· Labuan Foundation
· Labuan Trust
· Labuan Partnership (LP)/Limited Liability Partnership (LLP)
Application and Operational Requirements
The promoter and/or issuer must possess relevant qualifications and experience in the proposed business activity.
Compliance with ‘Economic Substance Requirements’ (ESR) as mandated by Labuan FSA and the Inland Revenue Board of Malaysia.
Submission of audited financial statements (where applicable) for the past 3 years for both the promoter and fund manager, along with the Information Memorandum (IM).
The IM must be provided to all prospective investors.
The fund may appoint a fund manager, administrator, or other service providers.
All key individuals (e.g., shareholders, directors, officers, trustees, etc.) must meet the Fit and Proper Person criteria set by Labuan FSA.
The promoter or fund entity is responsible for full compliance with all applicable Labuan laws, regulations, and reporting obligations.
Information Memorandum (IM) Requirements
The IM must provide full, accurate, and clear disclosure to enable investors to make informed decisions. It should include:
· General overview of the fund
· Investment strategy
· Financial information
· Subscription and redemption policies
· Disclosure of any material changes
Refer to the Guidelines on the Establishment of Labuan Mutual Funds and the Clarification Note for detailed requirements.
Tax Treatment under LBATA 1990
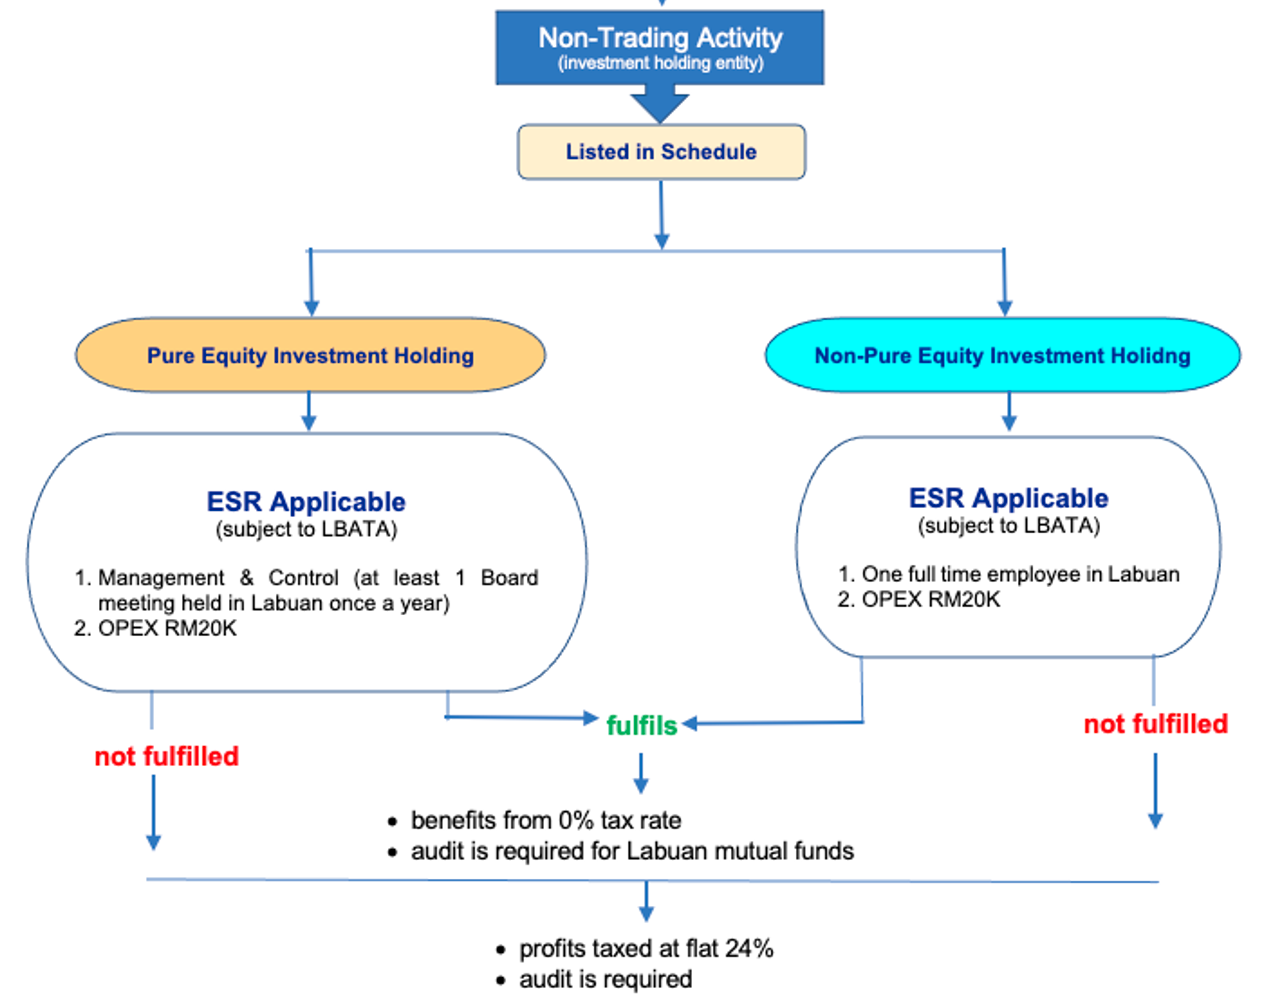
Income derived from non-trading activities by a Labuan private fund is exempt from tax, subject to compliance with ESR. Please refer to the ESR diagram for investment holding activities.
A non-trading activity means the entity holds investments rather than trading, and the substance test it faces depends entirely on what it holds. The flowchart below is the decision an adviser walks through, and it has only two branches.
If the entity holds nothing but stock and shares, it is pure equity investment holding. There is no full-time employee requirement at all: substance is demonstrated by management and control, evidenced by holding at least one board meeting in Labuan each year, plus RM20,000 of operating expenditure. If it holds anything else (derivatives, futures, debts, funds, REITs, property), it is non-pure equity, and one fit and proper full-time employee in Labuan is required alongside the same RM20,000.
The outcome either way is what matters commercially. Meet the requirement on your branch and the rate is 0%, with an audit required for Labuan mutual funds. Miss it and profits are taxed at a flat 24%, and the audit is still required, so failing the test costs you the tax and the compliance work.
Estimated Fees
Using a Labuan Company
· Formation fee starts from USD8,550.00
· Minimum annual maintenance USD4,100.00
Using a Labuan Partnership (LP or LLP)
· Formation fee starts from USD7,400.00
· Minimum annual maintenance USD3,500.00
Using a Labuan PCC
· Formation fee starts from USD11,250.00
· Minimum annual maintenance USD6,200.00
Notes to the estimated fees above:
The fees listed above do not include other costs such as meeting the ESR, office premises, fit and proper full-time employees based in Labuan, accounting services, e-invoicing, audit, human resources and payroll services, where applicable.
Applicant is recommended to engage lawyers to assist with the drafting of the Labuan entity’s constituent documents, such as the company M&A, partnership agreement, Information Memorandum, associated agreements and other ancillary documents. Drafting fees start from USD20,000.00.
Applicant may also be required to engage the services of a Labuan fund administrator for fund administration services, which includes fund accounting and bookkeeping, NAV calculation, subscription and redemption processing, etc. Estimated fees start from USD12,000.00 per annum.
Contact us for more information or if you require our assistance to establish your private fund in Labuan.
Please note that while we strive to offer comprehensive packages, specific client requirements or circumstances may necessitate adjustments. HMR Konsultan reserves the right to revise, add, or remove any items or fees without prior notice.