Economic substance
Labuan economic substance requirements
If your Labuan entity carries on an activity listed in the Schedule, you must employ a minimum number of fit and proper full-time employees in Labuan and incur a minimum annual operating expenditure there — or be taxed at a flat 24% instead of 3% or 0%.
Economic substance is the single most consequential compliance issue for a Labuan company. Malaysia introduced the requirements in 2019, abolishing the old RM20,000 flat tax option, and the regime has tightened since. The rule is simple in principle: to enjoy the preferential rate, the entity must be genuinely operating in Labuan.
What counts as adequate substance depends entirely on your business activity. Whether you are in scope at all depends on whether your activity is listed in the Schedule. Getting this assessment wrong is expensive — it is the difference between 3% and 24% on your net profits.
We maintain a decision flowchart mapping every branch of the rules, and we keep it current with each amendment. Use the ESR checker to find your position in about two minutes.
Substance minimums by activity type
| Trading activity, listed in the Schedule | Minimum 2 fit and proper full-time employees in Labuan and RM50,000 annual operating expenditure in Labuan. Benefits from the 3% rate; audit required |
|---|---|
| Non-trading — pure equity holding | Management and control in Labuan, and RM20,000 annual operating expenditure. Benefits from the 0% rate, and management accounts in the IRB's prescribed format are sufficient — audited accounts are not required |
| Non-trading — non-pure equity holding | Minimum 1 fit and proper full-time employee in Labuan and RM20,000 annual operating expenditure. Benefits from the 0% rate, and management accounts in the IRB's prescribed format are sufficient — audited accounts are not required |
| Failure to meet the requirements | Profits taxed at a flat 24%. Audit still required |
| Non-Labuan business activity (royalty or IP income) | Falls outside LBATA and is taxed under Malaysia's domestic Income Tax Act 1967 |
The Schedule: every activity and what it requires
Economic substance is not one rule. It is a list of 23 activities, each with its own minimum number of full-time employees in Labuan and its own minimum annual operating expenditure in Labuan. Find your activity below and you have your two numbers — miss either of them and the rate on your net audited profit becomes a flat 24% instead of 3% or 0%.
Three things are worth knowing before you read it. Codes 1 to 20 also require a licence from Labuan FSA — these are the regulated financial activities, and the licence is a separate application from the company itself. Codes 21 and 22 are the non-trading branch, for investment holding, and carry much lower thresholds. Code 23 is where most operating businesses land: the catch-all for service companies, at 2 employees and RM50,000.
If your activity is not in this list at all, the substance requirements do not apply to you — and following the judicial review decisions, an activity outside the Schedule still attracts the 3% rate under LBATA rather than being pushed into the domestic 24%.
Code 1 · Licence required
Labuan insurance business
Labuan insurer, reinsurer, takaful operator or retakaful operator — including general, life, reinsurance, Labuan takaful and retakaful windows, and captive insurance.
- Employees in Labuan
- 3
- Annual OPEX
- RM200,000
Code 2 · Licence required
Labuan underwriting manager or Labuan underwriting takaful manager
A person licensed to provide underwriting services, including the administration of the business, to one or more Labuan insurers.
- Employees in Labuan
- 4
- Annual OPEX
- RM100,000
Code 3 · Licence required
Labuan insurance manager or Labuan takaful manager
Provision of managerial and administrative services to Labuan (re)insurers and brokers.
- Employees in Labuan
- 4
- Annual OPEX
- RM100,000
Code 4 · Licence required
Labuan insurance broker or Labuan takaful broker
Broking direct insurance business (except direct Malaysian risks) with any insurance company whether or not licensed under the LFSSA; broking life insurance for high-net-worth Malaysians with LFSSA-licensed life insurers; and broking reinsurance of direct Malaysian risks transacted in Ringgit.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 5 · Licence required
Labuan captive insurer or Labuan captive takaful
Underwriting direct insurance or reinsurance (general or life) risks of the captive's own group, or third-party risks subject to Labuan FSA approval. Includes pure/single captives, group and association captives, master and subsidiary rent-a-captives, cell captives and multi-owner captives.
The higher employee requirement applies where the captive underwrites third-party risks, which is itself subject to Labuan FSA's approval.
- Employees in Labuan
- 2 for own-group risks; 3 where third-party risks are underwritten
- Annual OPEX
- RM100,000
Code 6 · Licence required
Labuan International Commodity Trading Company (LICT)
Trading of physical and related derivatives of petroleum and petroleum-related products including LNG, minerals, agriculture products, refined raw materials, chemicals, based minerals and coal, using Malaysia as the international trading base.
The RM3 million operating expenditure minimum is by far the highest in the Schedule — an order of magnitude above every other activity.
- Employees in Labuan
- 3
- Annual OPEX
- RM3,000,000
Code 7 · Licence required
Labuan bank, Labuan investment bank, Labuan Islamic bank or Labuan Islamic investment bank
Providing credit facilities and receiving deposits, investment banking services, building credit, credit token, development finance, leasing and digital banking business, or such other activities as approved by the Minister of Finance.
- Employees in Labuan
- 3
- Annual OPEX
- RM200,000
Code 8 · Licence required
Labuan trust company
Establishing or using a share transfer or share registration office; administering or managing property as agent, legal personal representative or trustee; soliciting or procuring business through an agent; maintaining an office, agency or branch; incorporating and registering Labuan entities; providing directors, officers, trustees, secretaries and registered offices; management and accounting services; and acting as lodging agent.
This is the licence HMR Konsultan itself holds — LT0072.
- Employees in Labuan
- 3
- Annual OPEX
- RM120,000
Code 9 · Licence required
Labuan leasing company or Labuan Islamic leasing company
Letting or sub-letting property on hire, with or without an option to purchase, including charters of ships on a bare-boat basis, plant, machinery, equipment or other chattel. Assets leased are expected to be high value or specialised.
Uniquely in the Schedule, the requirement scales with the number of related leasing companies in the group, and the expenditure minimum applies per company rather than per group.
- Employees in Labuan
- Per group of companies: 2 for up to 10 related leasing companies; 3 for 11–20; 4 for 21–30; plus 1 additional employee for each further increase of 10
- Annual OPEX
- RM100,000 for each Labuan leasing company
Code 10 · Licence required
Labuan credit token company or Labuan Islamic credit token company
Issuing a token in the form of a cheque, card, voucher, stamp, booklet, coupon or other document. For digital tokens, may create a blockchain ecosystem facilitating the use of digital assets — including for real estate investment, or for purchasing goods and services from participating merchants.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 11 · Licence required
Labuan development finance company or Labuan Islamic development finance company
Providing capital or other credit facility on terms requiring it to be used for industrial, agricultural, commercial or other economic development — including commencing new ventures or expanding existing ones.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 12 · Licence required
Labuan building credit company or Labuan Islamic building credit company
Providing a credit line — banking services.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 13 · Licence required
Labuan factoring company or Labuan Islamic factoring company
Acquiring debts owed to any person or institution at a discount, or such other business as approved by Labuan FSA.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 14 · Licence required
Labuan money broker or Labuan Islamic money broker
Acting as mediator, facilitator and matching clients with counterparties in money or foreign exchange markets, including digital currencies. Facilitates transactions and is paid in brokerage or commission fees.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 15 · Licence required
Labuan fund manager
Management services (acting as portfolio manager, managing acquisition or disposal of a portfolio of securities including funds, managing discretionary accounts including Labuan private funds); investment advice; administrative services including submissions to Labuan FSA and issuing prospectuses; and dealing in securities including quoting two-way prices and underwriting.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 16 · Licence required
Labuan securities licensee or Labuan Islamic securities licensee
Investment advice, administrative services including submissions to Labuan FSA and issuing prospectuses under the LFSSA/LIFSSA and LCA, and dealing in securities including quoting two-way prices and arranging sale or purchase of unlisted securities.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 17 · Licence required
Labuan fund administrator
Providing a mutual fund with administrative services or facilities, alone or with accounting services: fund accounting, calculation of NAV, fund valuations and reports, regulatory reporting, acting as intermediary between fund manager and investors, treasury and depository services, and processing subscriptions and redemptions.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 18 · Licence required
Labuan company management
Provision of treasury processing services for a group of related companies — arranging intra-group financing and factoring, managing cash and liquidity positions, and in-house investment or finance advisory — plus managerial services including back-room and middle-office services, acting as authorised representative for support services, and intermediation functions.
- Employees in Labuan
- 2
- Annual OPEX
- RM100,000
Code 19 · Licence required
Labuan International Financial Exchange
Listing and trading of financial instruments such as equities, investment funds and debt instruments, including listing of digital securities and trading of security tokens and cryptocurrencies, in conventional or Shariah-compliant form.
- Employees in Labuan
- 2
- Annual OPEX
- RM120,000
Code 20 · Licence required
Self-regulatory organisation or Islamic self-regulation organisation
An organisation regulating the operations, standards of practice and business conduct of its members or the users of its services, to better protect investors and consumers of securities or related services.
- Employees in Labuan
- 2
- Annual OPEX
- RM120,000
Code 21
Labuan entity undertaking investment holding activities other than pure equity holding
Investment holding in non-pure equity such as derivatives, futures, debts, funds, REITs and properties.
- Employees in Labuan
- 1
- Annual OPEX
- RM20,000
Code 22
Labuan entity undertaking pure equity holding activities
Investment holding in stock and shares.
This is the only activity in the Schedule with no full-time employee requirement — the substance test is satisfied by management and control, evidenced by the annual board meeting held in Labuan.
- Employees in Labuan
- Exempted from the employee requirement, but must hold a board meeting in Labuan once annually
- Annual OPEX
- RM20,000
Code 23
Other Trading Entities (OTE)
Administrative services, accounting services, legal services, back-office processing services, payroll services, talent management services, agency services, insolvency related services, and management services.
The catch-all for non-financial service businesses. This is the code most operating companies fall under, and the nine service definitions are set out in full below the table.
- Employees in Labuan
- 2
- Annual OPEX
- RM50,000
Code 23 in full: the nine service activities
Most non-financial businesses fall under code 23, and whether you are in scope turns on whether what you do matches one of these nine definitions. They are drawn from the Regulations, so read them against what your company actually does rather than against how you describe it commercially — the wording is what the assessment turns on.
- Administrative services
- Services pertaining to employee management, payroll management, property management, human resource management, financial planning, contract or subcontract management, facilities management, or proposal management.
- Accounting services
- Services pertaining to recording, analysing, summarising, or classifying financial, commercial and business transactions and information of a person or business.
- Legal services
- Conveyancing services, legal advisory services, litigation, legal representation services in any proceedings before any court, tribunal or other authority, and legal dispute resolution services including alternative dispute resolution.
- Back office processing services
- Services relating to settlements of receivables and payables, clearance, record maintenance, regulatory compliance or information technology related services which are usually performed by administration and support personnel who do not deal directly with clients.
- Payroll services
- Processing, calculation, payment and deduction of remuneration, benefits, tax, and statutory payment and/or issuance of payslip and tax statement.
- Talent management services
- The provision of human resource services to attract, onboard, develop, motivate, and retain employees.
- Agency services
- The provision of specific services on behalf of another group, business, or person pursuant to an agency agreement between the agent and its client.
- Insolvency related services
- Services related to administering company liquidations or winding up or personal bankruptcy.
- Management services
- Managing, organising, supervising, coordinating, monitoring, planning, controlling, and directing a client's resources in terms of human, financial, technology, physical and other resources.
If you fall under code 23, the requirement is 2 fit and proper full-time employees in Labuan and RM50,000 of annual operating expenditure in Labuan — the lowest of any trading activity in the Schedule, and the reason a service company is usually the cheapest in-scope structure to run.
Reference tables and diagrams
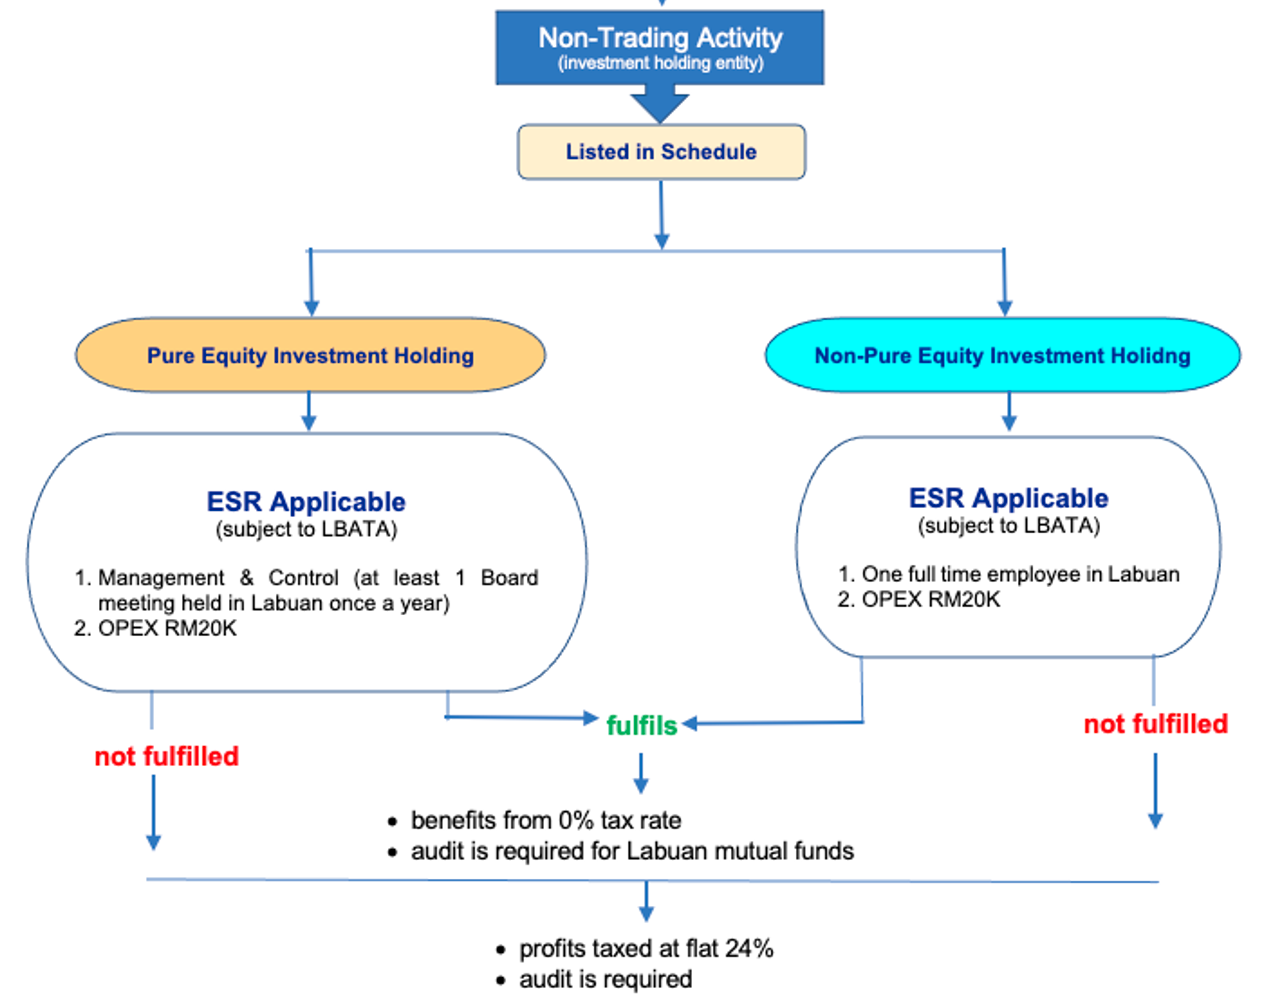
A non-trading activity means the entity holds investments rather than trading — and the substance test it faces depends entirely on what it holds. The flowchart below is the decision an adviser walks through, and it has only two branches.
If the entity holds nothing but stock and shares, it is pure equity investment holding. There is no full-time employee requirement at all: substance is demonstrated by management and control, evidenced by holding at least one board meeting in Labuan each year, plus RM20,000 of operating expenditure. If it holds anything else — derivatives, futures, debts, funds, REITs, property — it is non-pure equity, and one fit and proper full-time employee in Labuan is required alongside the same RM20,000.
The outcome either way is what matters commercially. Meet the requirement on your branch and the rate is 0%, with an audit required for Labuan mutual funds. Miss it and profits are taxed at a flat 24%, and the audit is still required — so failing the test costs you the tax and the compliance work.
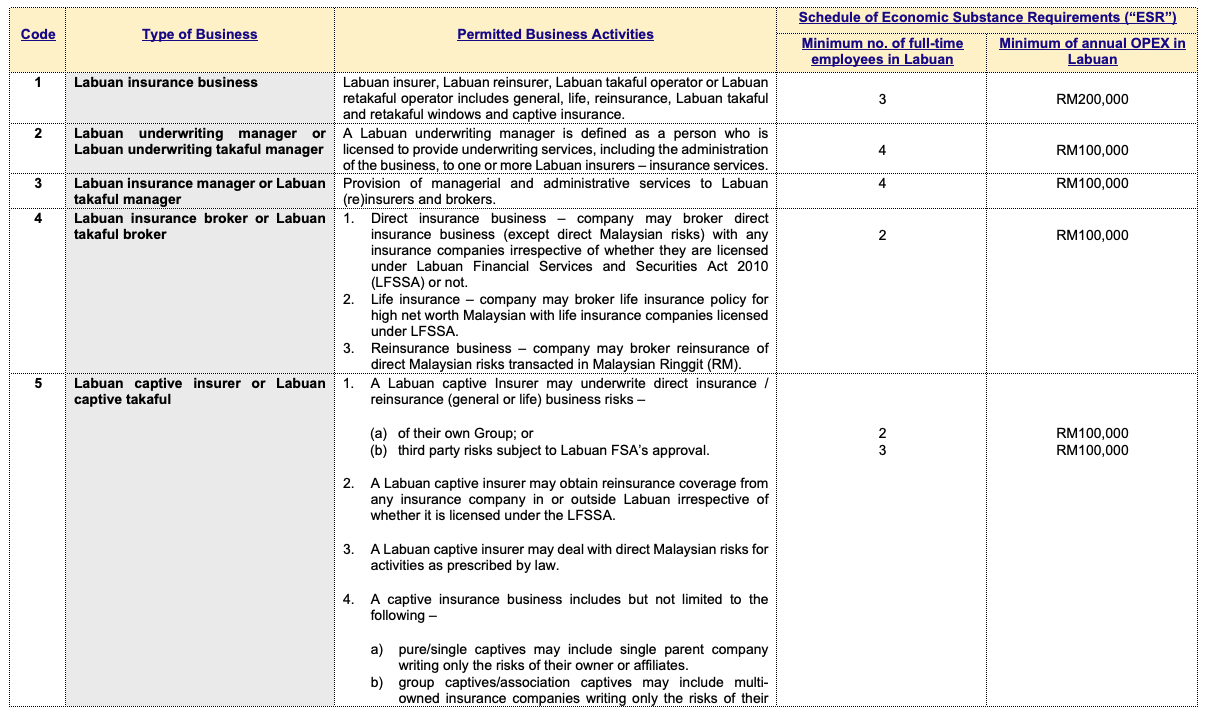
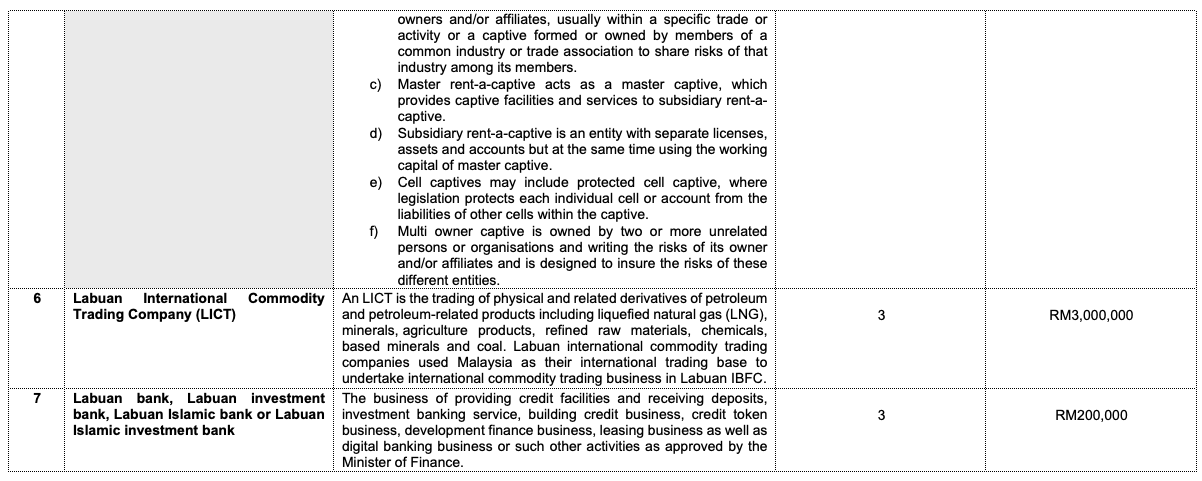
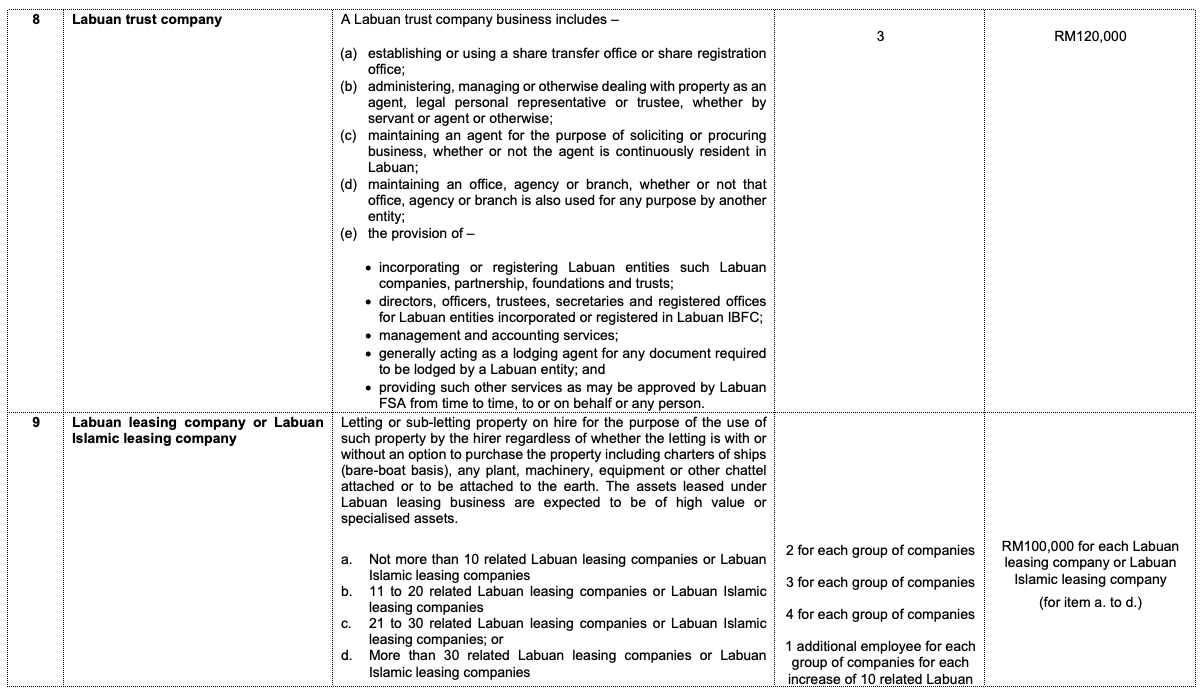
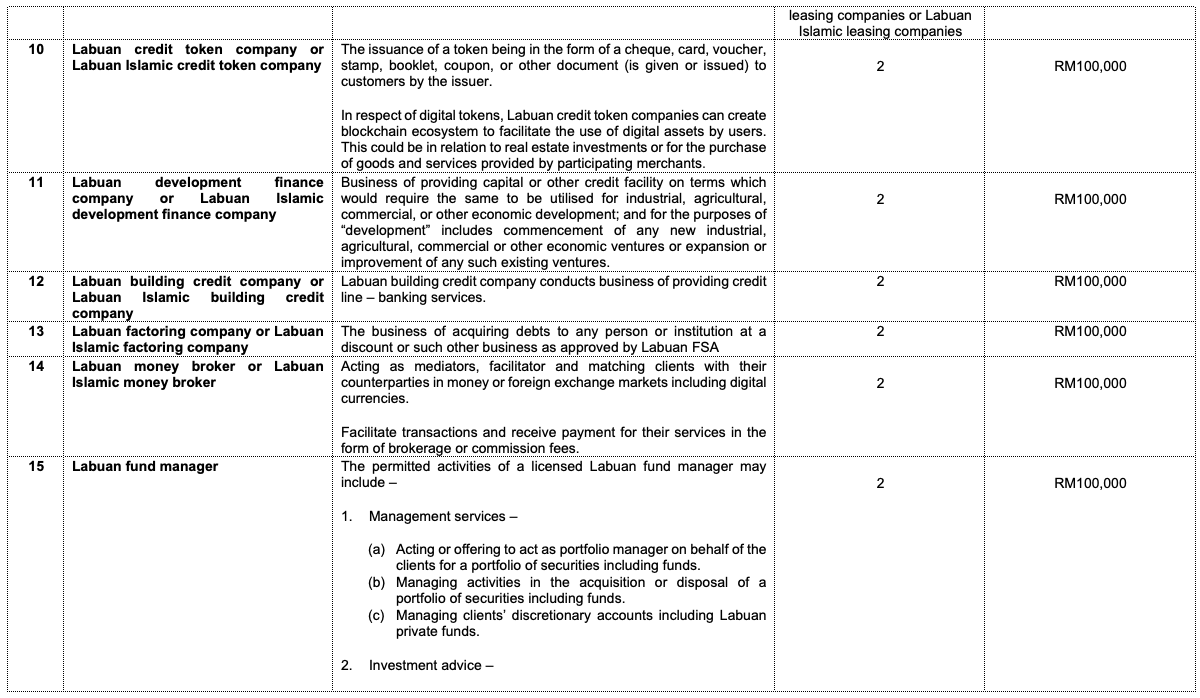
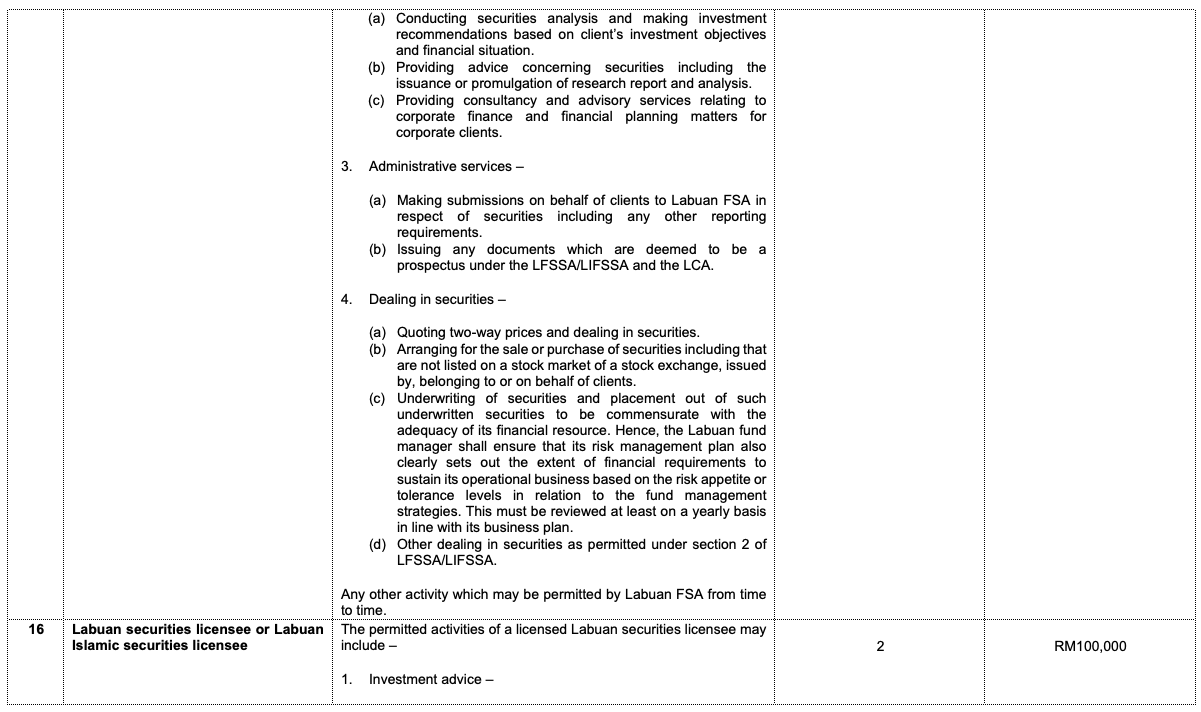
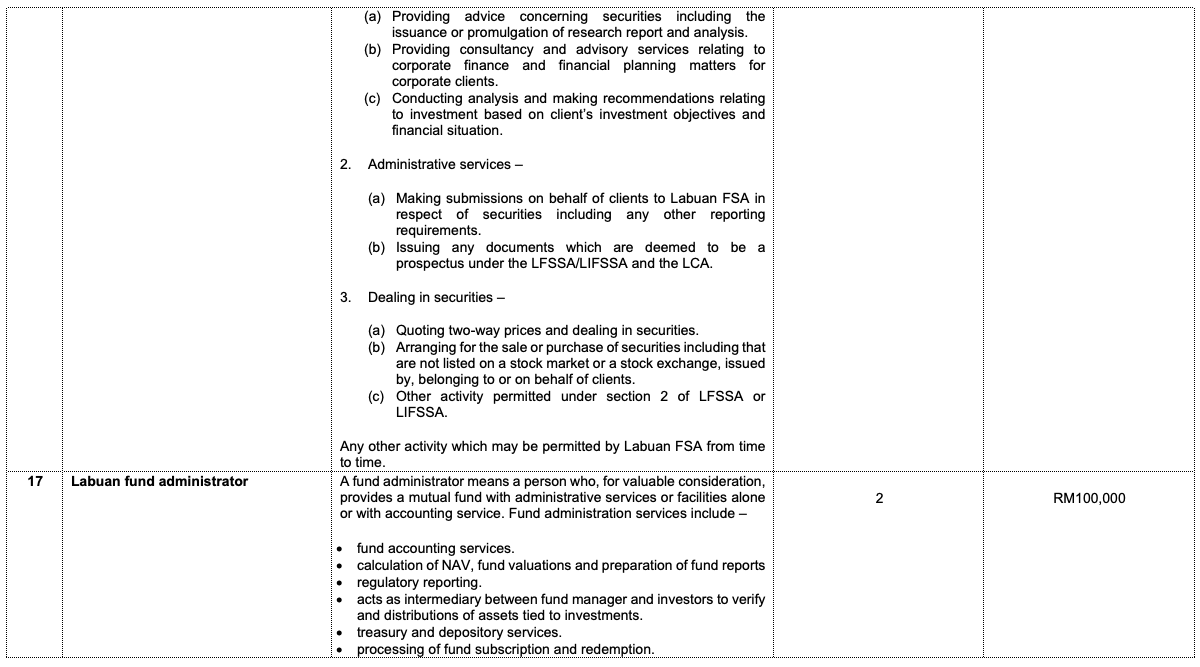
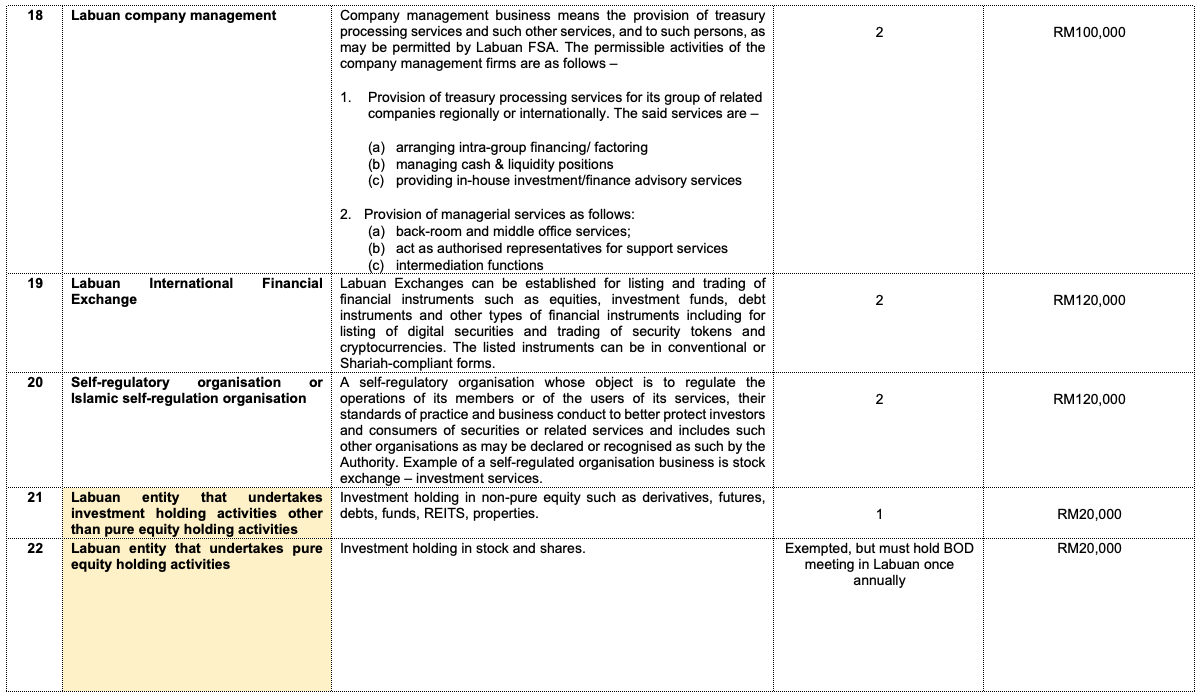
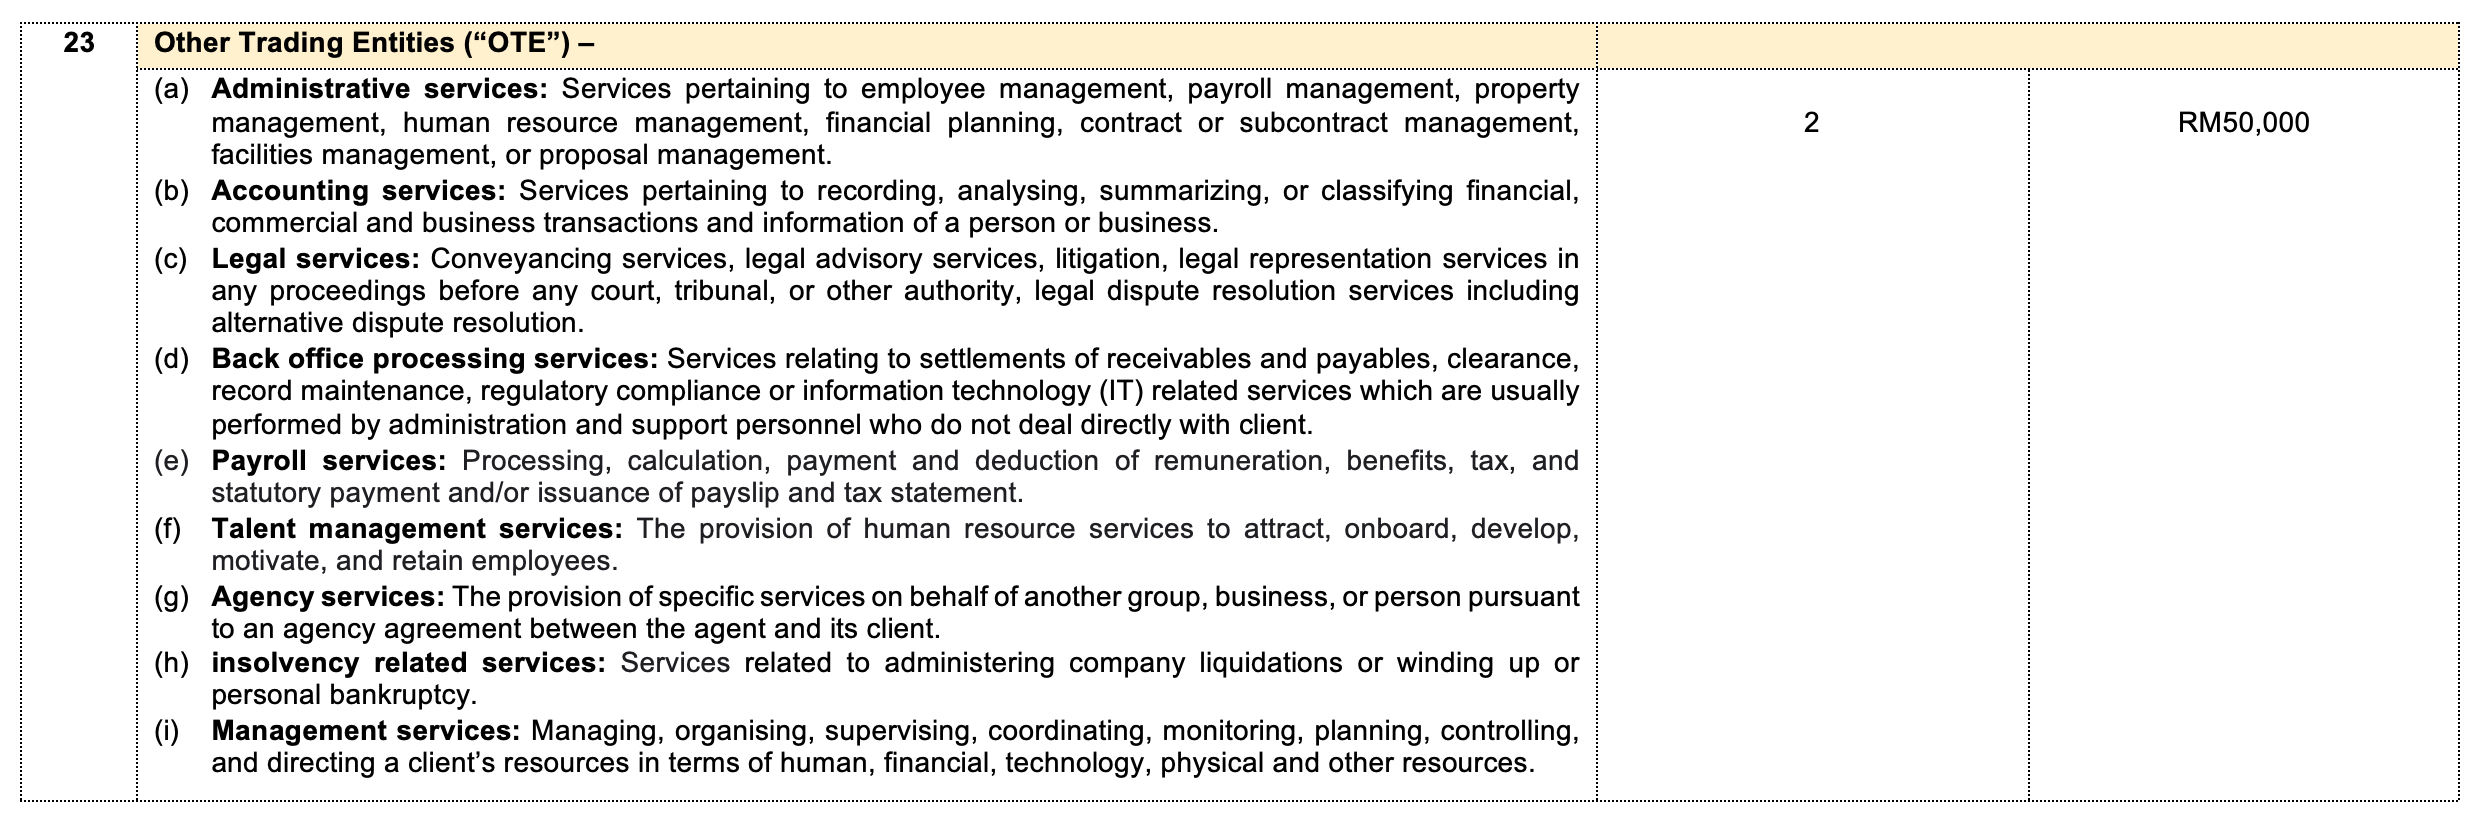
What follows is the Schedule itself, reproduced as published. Each row gives an activity code, what that business is permitted to do, and the two numbers that decide your tax position — the minimum fit and proper full-time employees you must have in Labuan and the minimum you must spend there each year.
It runs to eight pages. If you only need your own two numbers, the searchable table above gives them without the statutory wording; these pages are here so you can read the full definition of your activity, which is what an assessment will actually turn on.
Meeting the requirements in practice
Advertise the vacancy
Job vacancies are advertised on the MYFutureJobs portal, which also notifies SOCSO of the vacancy. This is the first step in hiring the full-time employees your substance obligation requires.
Stamp the employment contract
The employment contract must be stamped within 30 days of execution, done through e-Stamp on the MyTax portal. The minimum gross monthly salary for a full-time employee in Malaysia is RM1,700.00. That is the legal minimum, not a benchmark for substance: staff supporting a Labuan business activity are normally paid more, in line with their role and experience.
Register as an employer
Register with EPF (KWSP) via i-Akaun and with SOCSO through the ASSIST portal — which covers both SOCSO and the Employment Insurance System. Register with the Inland Revenue Board for monthly tax deductions, and with HRD Corp where the levy applies.
Notify the IRB of the new employee
Form CP22 must be submitted to the Inland Revenue Board within 30 days of the employee commencing employment.
Run payroll and pay contributions
EPF, SOCSO, the HRD Corp levy and monthly tax deductions are all due before the 15th of the following month. Late payment attracts penalties and, more importantly here, undermines the evidence that the employee is genuinely full-time in Labuan.
Meet the annual employer deadlines
The EA form must be given to each employee before the last day of February. Form E together with CP8D must be filed with the IRB by 31 March of the following year, through MyTax.
Handle departures correctly
Form CP22A must be filed within 30 days of an employee ceasing employment. Where an expatriate is leaving Malaysia for more than three months, Form CP21 must be filed at least 30 days before departure. EPF and SOCSO exit dates must also be updated.
How we help
- Assessing whether your activity falls within the Schedule, and which branch applies
- All-in-one economic substance services — office, recruitment, onboarding and payroll
- Dealing with the local labour authority and advising on employment regulations
- Registering the company as an employer with EPF, SOCSO, EIS, the IRB and HRD Corp (depends on headcount)
- Running monthly payroll for your Labuan-based staff
- Filing CP22, CP22A, CP21, the EA forms and Form E with CP8D on time
- Structuring operating expenditure so it counts toward the minimum
- Remediation where a company has fallen out of compliance
Frequently asked questions
How do I know if my company is in scope?
It depends on whether your business activity appears in the Schedule to the Labuan Business Activity Tax Act. Our ESR checker walks you through the same decision tree our advisers use and tells you which branch you fall into.
What happens if I do not meet the requirements?
A Labuan entity that is in scope but fails to meet the substance requirements is taxed at a flat rate of 24% on its profits, instead of 3% or 0%, and audited accounts are required. In addition, your Labuan entity may not be eligible to enjoy the applicable tax exemptions.
Do the employees have to be physically in Labuan?
Yes. The requirement is for fit and proper full-time employees physically based in Labuan, and for operating expenditure incurred in Labuan. This is exactly why a firm with a real Labuan office and local hiring experience matters.
Can you provide the employees for us?
We provide all-in-one economic substance services covering recruitment, onboarding with the local labour authority, employment regulation advice and monthly payroll — so the administrative burden sits with us rather than with you.
Have the rules changed recently?
Yes, repeatedly. The position on activities that are not listed in the Schedule is not yet settled, so talk to us before relying on any assumption about yours.
Which non-financial activities are in scope, exactly?
Nine service activities are defined in the Regulations. Administrative services: employee management, payroll management, property management, human resource management, financial planning, contract or subcontract management, facilities management, or proposal management. Accounting services: recording, analysing, summarising or classifying financial, commercial and business transactions. Legal services: conveyancing, legal advisory, litigation, legal representation before any court or tribunal, and alternative dispute resolution. Back-office processing services: settlements of receivables and payables, clearance, record maintenance, regulatory compliance and IT-related services performed by staff who do not deal directly with clients. Payroll services: processing, calculation, payment and deduction of remuneration, benefits and tax, and issuance of payslips and tax statements. Talent management services: attracting, onboarding, developing, motivating and retaining employees. Agency services: providing specific services on behalf of another group, business or person under an agency agreement. Insolvency related services: administering company liquidations, winding up or personal bankruptcy. Management services: organising, coordinating, supervising, monitoring, planning, controlling and directing a client's human, financial, technology and physical resources.
What are the minimum thresholds for an in-scope trading activity?
Two fit-and-proper full-time employees in Labuan and RM50,000 of annual operating expenditure in Labuan. Activity codes 1 to 20 additionally require licensing from Labuan FSA. The full schedule of activities, with the minimum employees and expenditure for each code, is reproduced above.
What if the company makes a loss?
If the company reports an audited loss there is no tax payable, whether or not the substance requirements were met.
What does hiring in Labuan actually involve?
More than a payslip. You advertise on MYFutureJobs, stamp the employment contract within 30 days, register with EPF, SOCSO, EIS, the IRB and HRD Corp (depends on headcount), file Form CP22 within 30 days of the employee starting, pay contributions before the 15th of each following month, issue EA forms by the end of February and file Form E with CP8D by 31 March. The minimum gross monthly salary is RM1,700.00. That is the legal minimum, not a benchmark for substance: staff supporting a Labuan business activity are normally paid more, in line with their role and experience. We handle all of it — see the process above.
Speak to us
We are the licensed trust company, so the advice and the filing come from the same place.
Talk to our KonsultanSources
The primary documents this page relies on, linked to the authority that issued them. If one has moved, tell us and we will correct it.
- Guidelines on tax-related matters, including substance requirements (opens in a new tab)
Labuan FSA · Guideline
The full-time employee and operating expenditure minimums, by activity, are published here.
- Acts administered by Labuan FSA — including the Labuan Companies Act 1990, the Labuan Business Activity Tax Act 1990 and the Labuan Financial Services and Securities Act 2010 (opens in a new tab)
Labuan FSA · Legislation
The substance regime sits under LBATA 1990 and the regulations made under it.
Last reviewed 4 August 2026
Whilst considerable care has been taken to ensure the information contained within this page is accurate and up to date, no warranty is given as to the accuracy or completeness of any information and no liability is accepted for any errors or omissions in such information. The information given in this page is based on our present understanding of the current laws, guidelines and regulations and may therefore be subject to change without notice.
Ready when you are
Talk to the firm that holds the licence.