Labuan financial business activities
Labuan fund management and private funds
A Labuan private fund can be established for a limited circle of sophisticated investors, and fund management as a business activity requires its own Labuan FSA licence.
Labuan offers fund structures aimed at private and institutional investors, with private funds subject to lighter requirements than public ones. Fund management — managing those assets as a business — is separately licensed under the Labuan Financial Services and Securities Act 2010.
We have published a detailed summary of Labuan private funds, prepared on the basis of the prevailing laws and Labuan FSA guidelines, including an indicative fee schedule. It is the most detailed public resource we produce on this structure.
What to expect
| Governing law | Labuan Financial Services and Securities Act 2010 |
|---|---|
| Private fund | Available to a defined circle of investors, with lighter requirements than a public fund |
| Investor thresholds | Either up to 50 investors each subscribing a minimum initial investment of RM250,000, or an unlimited number of investors each subscribing a minimum of RM500,000 |
| Eligible vehicles | A Labuan company, a Protected Cell Company (PCC), a foundation, a trust, or a partnership / limited liability partnership |
| Registration | A Labuan private fund is not licensed in the way a public fund is — a written notification to Labuan FSA together with lodgement of the Information Memorandum suffices |
| Information Memorandum | Must be given to all prospective investors, covering a general overview, the investment strategy, financial information, subscription and redemption policies, and disclosure of any material changes |
| Supporting documents | Audited financial statements for the past 3 years for both the promoter and the fund manager, plus fit-and-proper assessment of all key individuals |
| Fund management | Managing fund assets as a business is a separately licensed activity |
| Tax | Income derived from non-trading activities by a Labuan private fund is exempt from tax, subject to compliance with the economic substance requirements |
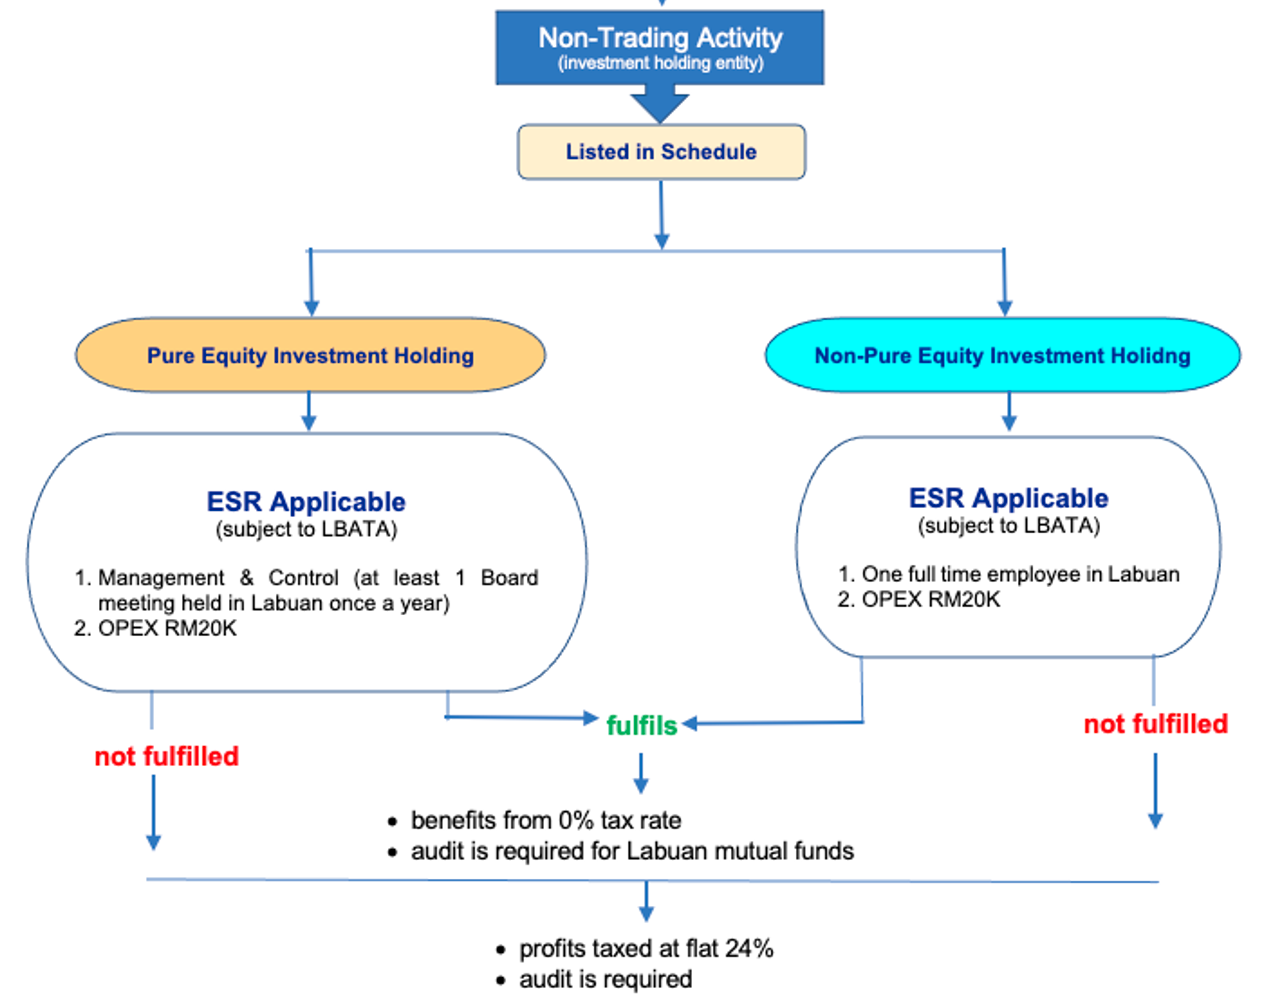
| Economic substance | Applies. For a non-trading investment holding activity: pure equity holding requires management and control with at least one board meeting in Labuan each year plus RM20,000 operating expenditure; non-pure equity holding requires one fit and proper full-time employee in Labuan plus RM20,000 operating expenditure. See the decision flowchart below |
Reference tables and diagrams
A non-trading activity means the entity holds investments rather than trading — and the substance test it faces depends entirely on what it holds. The flowchart below is the decision an adviser walks through, and it has only two branches.
If the entity holds nothing but stock and shares, it is pure equity investment holding. There is no full-time employee requirement at all: substance is demonstrated by management and control, evidenced by holding at least one board meeting in Labuan each year, plus RM20,000 of operating expenditure. If it holds anything else — derivatives, futures, debts, funds, REITs, property — it is non-pure equity, and one fit and proper full-time employee in Labuan is required alongside the same RM20,000.
The outcome either way is what matters commercially. Meet the requirement on your branch and the rate is 0%, with an audit required for Labuan mutual funds. Miss it and profits are taxed at a flat 24%, and the audit is still required — so failing the test costs you the tax and the compliance work.
Indicative fees
Formation and annual maintenance depend on which vehicle you use for the fund. Figures below are indicative starting points; current figures are confirmed in writing at pre-assessment.
- Labuan company — formation
- From USD 8,550, with minimum annual maintenance of USD 4,100
- Partnership / LLP — formation
- From USD 7,400, with minimum annual maintenance of USD 3,500
- Protected Cell Company — formation
- From USD 11,250, with minimum annual maintenance of USD 6,200
- Legal drafting
- From USD 20,000
- Fund administrator
- From USD 12,000 per annum
These fees exclude the cost of meeting the economic substance requirements — office premises, fit and proper full-time employees based in Labuan and the annual operating expenditure minimum — which for most funds is the larger recurring number.
How we help
- Pre-assessment of the proposed business activity against Labuan FSA's criteria
- Advice on the latest regulatory and statutory requirements for the licence
- Preparation of the application, business plan and supporting documents
- Managing your interaction with Labuan FSA throughout the assessment
- Incorporating and maintaining the licensed entity itself — registered office, resident secretary, statutory records
- Post-licensing compliance: economic substance, reporting, accounting and audit
Frequently asked questions
What is the difference between a private fund and a public fund?
A Labuan private fund is offered to a limited circle of investors and is subject to lighter requirements than a fund offered to the public. Which applies depends on how the fund is offered and to whom.
Do I need a separate licence to manage the fund?
Fund management is a licensed business activity in its own right, distinct from establishing the fund. Whether you need one depends on who manages the assets and from where.
Speak to us
We are the licensed trust company, so the advice and the filing come from the same place.
Talk to our KonsultanSources
The primary documents this page relies on, linked to the authority that issued them. If one has moved, tell us and we will correct it.
- Labuan capital markets — Labuan FSA overview, including fund management (opens in a new tab)
Labuan FSA · Regulator
Fund management sits within Labuan FSA's capital markets framework.
- Guidelines for Labuan capital markets, including fund management (opens in a new tab)
Labuan FSA · Guideline
The standing guidelines a fund management application is assessed against.
- Acts administered by Labuan FSA — including the Labuan Companies Act 1990, the Labuan Business Activity Tax Act 1990 and the Labuan Financial Services and Securities Act 2010 (opens in a new tab)
Labuan FSA · Legislation
Last reviewed 4 August 2026
Whilst considerable care has been taken to ensure the information contained within this page is accurate and up to date, no warranty is given as to the accuracy or completeness of any information and no liability is accepted for any errors or omissions in such information. The information given in this page is based on our present understanding of the current laws, guidelines and regulations and may therefore be subject to change without notice.
Ready when you are
Talk to the firm that holds the licence.